After a Drop Comes the Bounce
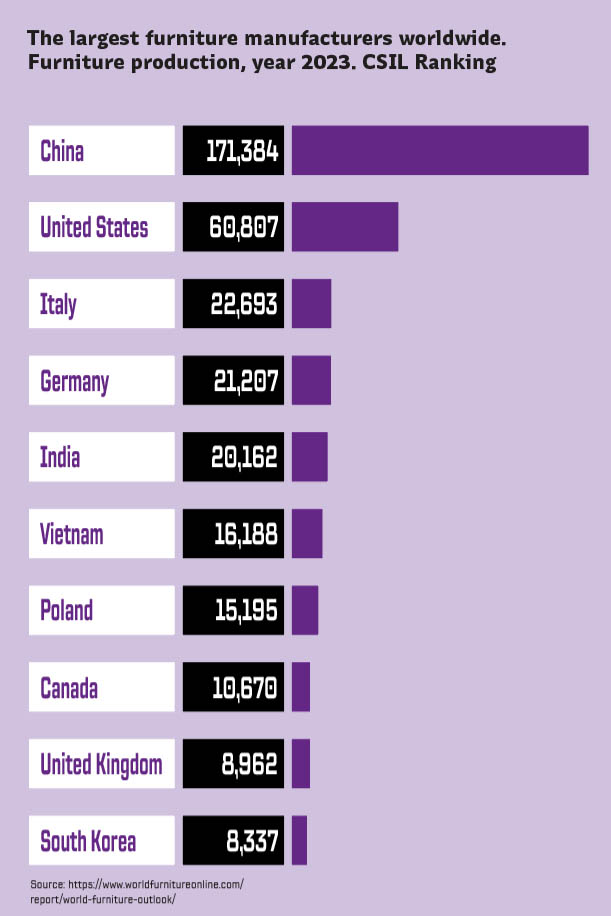
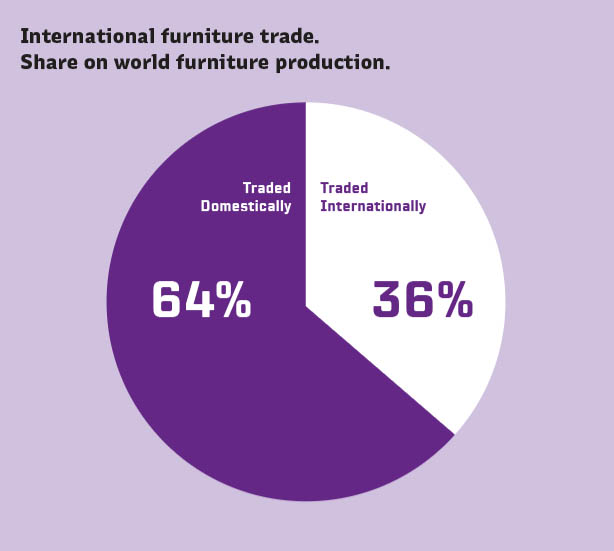
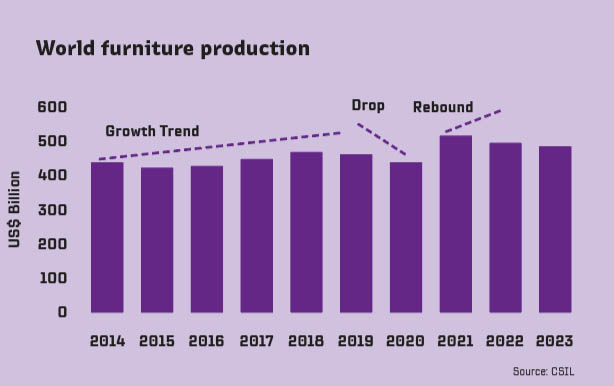
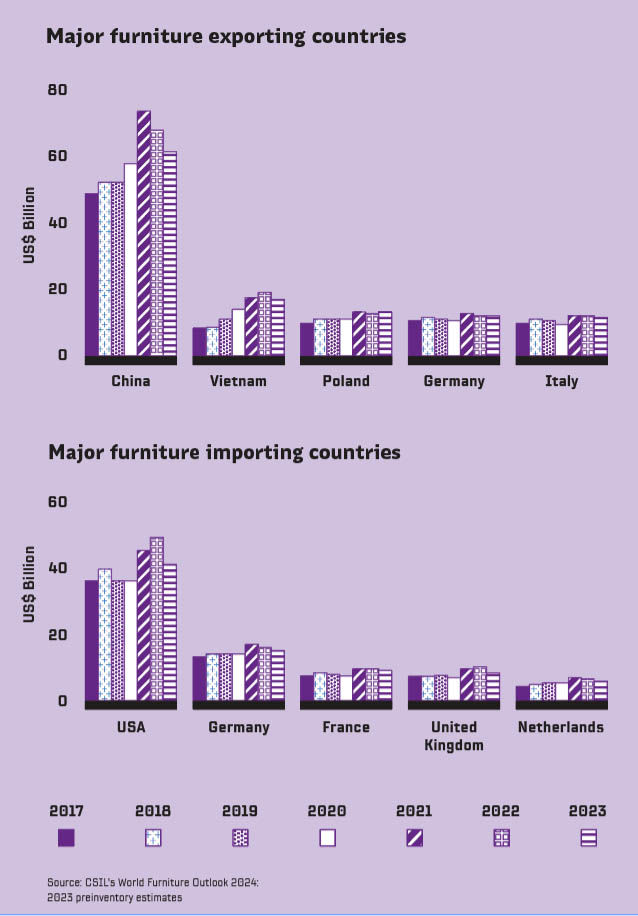
When approaching the furniture industry statistics, several aspects need to be highlighted. Firstly, the sector relevance: global furniture production is worth approximately $500 billion according to CSIL World Furniture Outlook estimates, making it a large industry. Looking at the main actors, China is the largest producer (34 per cent of world output), followed by the United States (16 per cent) and Italy (5 per cent). Canada ranks in the eighth position in CSIL ranking. Secondly, its global dimension with around one-third (36 per cent) of world production traded internationally (that is, products that cross national borders and are purchased in a foreign market). Thirdly, the sectors’ historical growth trend: the value of the global industry has grown by over 10 per cent in the last decade, in value.
 Although the industry was historically growing, the last two years were marked by a difficult economic and geopolitical context. After the rebound of activities in 2021, according to CSIL data both global furniture production and international trade contracted in 2022 and 2023. The global furniture sector was suffering because of multiple challenges including the slowdown of economic growth, rising inflation and interest rates; conflicts and tensions in the geopolitical context, difficult functioning of supply chains and logistics, and trade tensions. Additionally, market deterioration with consumers’ budget erosion because of inflation and weakening furniture demand in favour of other products, especially services such as leisure and tourism, put additional pressure on the industry. All these aspects have led in recent years to a context of considerable uncertainty.
CSIL forecasts are for a gradual, but not immediate, reversal of the trend. Economic growth forecasts are becoming more positive with global GDP growth anticipated at a rate exceeding 3 per cent in the coming years along with a gradual restoration of income levels and consumer purchasing power which should, among others, favour furniture demand. More specifically, CSIL foresees a more pronounced growth of the Asian furniture markets, a progressive stabilization in North America already in 2024, and an improving, but still delicate situation, in Europe before an expected stabilization from 2025 onwards. Downside risks to growth include the persistence of geopolitical uncertainties, and the intensification of trade tensions (e.g. trade barriers to international trade), and logistical and transportation pressures (e.g. those in the Red Sea).
 What CSIL observes is that, in this context, furniture company strategies and investments are continuously evolving and leading to careful reflection on sourcing strategies and dynamics to reduce business risks and vulnerabilities. For example: shortening supply chains, nearshoring, careful evaluation and selection of suppliers are examples of topics becoming more and more relevant.
Alessandra Tracogna is a partner and senior market researcher at CSIL. With over 40 years of activity in market research focussed on the furniture sector, CSIL has built a unique observatory by collecting and analyzing industry and company data on a global scale for over 100 countries worldwide. www.worldfurnitureonline.com